New PayID pokies in Australia: what the deposit rail cannot make legal
30 October 2026 — figures verified against the ACMA’s published blocking actions and the Australian Payments Plus PayID register.
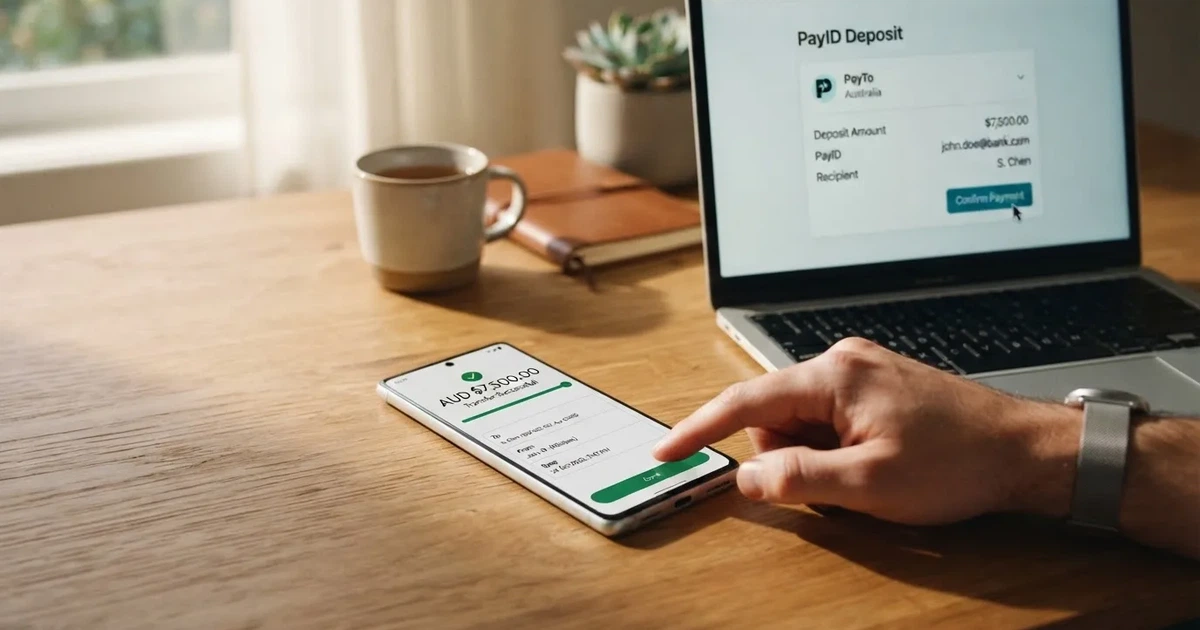
A new pokies site that takes PayID feels modern. The deposit clears in seconds through the same banking app an Australian already uses for groceries, the bonus headline is in Australian dollars, and the cashier screen reads like an extension of the bank rather than a foreign operator. The speed is real — the legitimacy it implies is not. No online casino or online pokies product is licensed in Australia, regardless of which deposit rail the cashier offers. PayID is a payments tool, not a consumer protection. The point of this page is to make that gap visible, to put a number on what offshore pokies cost Australian households, and to set out what an Australian reader actually controls when a PayID transfer is sitting in front of them.
The brands listed below are not a ranking and not a recommendation. They appear because the Australian Communications and Media Authority (ACMA) issued a formal warning over each of them — every one an offshore operator that offered prohibited interactive gambling services to people in Australia. Where the ACMA has acted, the same operator’s casino games remain illegal to provide, whatever licence the site’s footer displays.
Table of Contents
- How PayID actually settles — and what that does for a pokies site
- Why no Australian can be told the site is safe
- The eleven brands the ACMA has acted against
- What it costs the country — and what it can cost the player
- What an Australian player actually controls
- The 2026 reform — law with a start date, not yet in force
- What the speed is actually worth
- Frequently asked questions
How PayID actually settles — and what that does for a pokies site
PayID is an easy-to-remember alias for a bank account: a mobile number, an email address, an ABN or an Organisation Identifier, maintained by Australian Payments Plus (AP+) and built into the online banking of more than 100 Australian financial institutions. When a payer types in a PayID, the banking app shows the name of the account holder before the transfer is sent — the single check that protects against typos, mistaken payments and scams. PayID itself sits on top of Australia’s New Payments Platform (NPP), which the Reserve Bank of Australia oversees and which has settled transactions individually, close to real time, since it went live in February 2018. As of April 2025, more than 25 million PayIDs were registered across the country. The mechanics are ordinary: AP+ runs them, the RBA oversees the underlying platform, and any Australian bank can send through Osko to a PayID the same way it sends to a BSB and account number — and arrive in under a minute, twenty-four hours a day, weekends included.
The technology is unspectacular, which is what makes it useful as a marketing prop. A casino cashier that takes PayID inherits three things from the NPP without paying for them:
- Speed. The “instant deposit” line on a new pokies site is, in most cases, the literal NPP speed at the bank end. There is no special PayID casino rail; the casino just types its own PayID into the customer’s banking app.
- Familiarity. The customer never leaves their bank’s environment. The trust the customer places in Westpac, CBA or ANZ is borrowed by the offshore operator the moment the cashier screen reads “deposit via PayID”.
- Low friction. No card number, no merchant surcharge, no crypto wallet, no third-party e-wallet. The customer’s first deposit takes roughly the time it takes to type a phone number and tap send.
AP+ itself warns directly about the way offshore gambling sites borrow this familiarity. “If you are asked to send PayID money to an illegal gambling site, it is almost certainly a scambling website” — scambling being AP+’s own term for illegal online gambling platforms that trick people into gambling on a scam site through social media and messaging apps. AP+ tells anyone who thinks they have been scambled to contact their financial institution first. PayID never contacts a customer directly; emails or text messages claiming to be from PayID are scams, and PayID never asks anyone to send money in order to receive money or to “upgrade” an account. The trust the cashier inherits is real customer trust in the bank — and it is being borrowed, not earned.
What the bank still controls
Speed is the bank’s. The decision about whether the transfer is allowed at all sits with the customer’s own bank, not with the casino. Westpac’s gambling block refuses authorisation of transactions registered under the merchant category code ‘Betting/Casino Gambling’ on eligible personal credit and debit cards. ANZ’s gambling block, activated inside the ANZ app, extends the same block to digital-wallet transactions such as Apple Pay on an eligible card. Once ANZ’s block is on, removing it requires a forty-eight-hour waiting period — and ANZ warns that not all gambling transactions will be blocked, and that some non-gambling transactions may be blocked in error. These are blunt tools. They cut the rail, not the casino’s existence; a customer who switches banks, opens a new account, or uses a card the block does not cover has not changed whether the offshore site itself is legal.
Surcharges and the card alternatives
A reader comparing PayID with a card deposit on a new pokies site will sometimes find the PayID route advertised as “no fees” while the card route carries a surcharge. The gap is mostly the merchant’s own card-processing costs. The Reserve Bank’s July 2025 review proposes removing surcharges only on eftpos, Mastercard and Visa, leaving American Express outside the proposed surcharge ban; Apple Pay itself does not charge consumers for using it — any surcharge on an Apple Pay transaction is the merchant’s card-processing fee rather than a fee from Apple. PayID is not a surcharge-free product because the casino is generous; PayID is surcharge-free because there is no card network on top of it to charge one. The same deposit, paid by Visa, would cost the casino more to accept, and that cost typically lands back on the customer as a percentage surcharge.
Credit cards and crypto at licensed wagering sites
Under the Interactive Gambling Act 2001 as amended in 2023, Australian-licensed online wagering services cannot accept credit cards or other credit-related products as payment. Digital currency and credit-related products were banned as payment for licensed online wagering from 11 June 2024, with penalties up to A$247,500 for the operator. Legal deposit routes for licensed wagering are debit card, bank transfer, PayID and Osko, and BPAY. A pokies site asking an Australian for a credit card number or a crypto wallet address is operating outside the Australian rules regardless of what its footer says — the deposit rail does not bring the offer into scope. For an offshore casino, none of this matters: the credit-card ban binds Australian-licensed wagering services only, and an offshore operator is not licensed.
Why no Australian can be told the site is safe
The licence line is where the marketing does its hardest work, and where it does the most damage.
The Interactive Gambling Act in plain terms
The Interactive Gambling Act 2001 (IGA), strengthened by the Interactive Gambling Amendment Act 2017, makes it an offence to provide online casino games, online pokies or in-play betting to a person physically in Australia. No state or territory licenses these products. What can be licensed is wagering on racing and sport placed before the event, lotteries and keno. The Australian-licensed bookmakers — Sportsbet, Bet365 and Ladbrokes among them — sit under the Northern Territory Racing and Wagering Commission (NTRWC), which regulates 52 online bookmakers and meets once a month in Darwin with no full-time staff. The commission’s role is licensing wagering operators for Northern Territory tax reasons. It does not, and cannot, license a pokies site.
An offshore pokies site that displays a Curaçao or Anjouan licence number at the bottom of its homepage is licensed somewhere — just not in Australia, and not for the purpose of taking Australian customers. The licence is a permission the foreign regulator has granted the foreign operator; it does not bind the foreign regulator to act on an Australian complaint, and it gives an Australian no recourse if a withdrawal is refused. The footer is real. The protection it implies is not.
Who enforces it, and how often
The ACMA investigates breaches, issues formal warnings, and directs Australian internet service providers to block illegal sites. Two enforcement numbers frame the whole offshore market:
- 1,751 illegal gambling and affiliate marketing websites blocked since the first blocking request in November 2019.
- 230+ unlicensed gambling services that have left the Australian market since enforcement was strengthened in 2017.
That is the ACMA’s own running total, reported in June 2026. In the round reported on 26 June 2026 alone, the ACMA asked ISPs to block twelve more illegal gambling websites: 7Signs, ChromaBet, Donbet, Duospin, Freshbet, Slots Gem, Jacks Club, Lucky Start, Pointsbetz, Spinrise, Vinyl Casino and Wildsino. A blocking request does not require a fresh breach; once a site is on the list, the ISP applies the block and Australian customers see a dead page on a balance that may still be sitting on it.
How fast the block list has grown
Between the first ACMA blocking request in November 2019 and the June 2026 total of 1,751 blocked sites, the average run-rate lands somewhere in the order of twenty-two blocked sites a month — roughly 265 a year, against a market that was already declared illegal in 2017. That is the arithmetic of an enforcement regime catching up to an industry that was running ahead of it: blocks added faster than the ACMA has staff to investigate, and roughly one new illegal site blocked for every two days of the past six and a half years. The pace is a band, not a single number — the early years were slower and the recent years faster — but the order of magnitude is the point. The ACMA is not catching the offshore industry in a slow drift; the offshore industry is being added to a block list at a rate of hundreds of sites a year, and the ACMA has acted on each of the eleven brands named in the operator section of this page.
What the ACMA actually publishes
A formal warning is not a court action. The ACMA publishes the operator’s name, the brand, the section of the IGA breached and the date. The warnings do not, on their own, remove a site from the internet. They are the recorded basis on which a later blocking request is made, and they are the most concrete piece of evidence a reader can use to check whether a brand they are looking at has already been through the regulator’s process. Eleven of the most-advertised offshore pokies brands in Australia have been through it.
The eleven brands the ACMA has acted against
Each entry below is what the ACMA itself has published. The brand, the operator named by the ACMA, the date the formal warning was issued, and the wider history if the same operator has been warned before. The set is not a ranking, and a brand appearing earlier in the list is no safer, more legitimate or more recommended than one appearing later.
RocketPlay
The ACMA issued a formal warning to Pulsup Ltd over RocketPlay in March 2026. Dama N.V., the same operator group RocketPlay sits under, was warned by the ACMA in May 2022 over a portfolio of casino brands. Two warnings across four years on related entities, both for offering prohibited interactive gambling services to Australians. The March 2026 action names the Australian-facing mirror directly. This site has no Australian operating permission.
Level Up Casino
The ACMA issued a formal warning to Dama N.V. over Level Up in May 2022 as part of a six-brand warning that also covered Bambet, Dazard, Rocketplay, Wild Tornado and Cobra Casinos. Level Up is the same entity, same date, same IGA breach. The site continues to advertise to Australian customers. The brand operates entirely without local authorisation.
Woo Casino
The ACMA issued a further formal warning to Dama N.V. over Woo Casino in March 2025. Woo is the second Dama N.V. brand the ACMA has named in a fresh round after the 2022 portfolio warning — three years later, on the same operator. No Australian regulator recognises this site as legal.
Spirit Casino
The ACMA issued a formal warning to Dama N.V. over Spirit Casino in May 2025, two months after the Woo Casino warning. The Dama N.V. cluster is the most warned operator group in the ACMA’s recent register, with three rounds spanning 2022 and 2025. Local enforcement against this brand remains active.
National Casino
The ACMA issued a formal warning to Consolutetish S.R.L. over National Casino in July 2025. National Casino was already on the ACMA’s radar through earlier AUSTRAC and other public-record entries. It is blocked to Australian IP addresses by many ISPs.
Bizzo Casino
The ACMA issued a formal warning to Consolutetish S.R.L. over Bizzo Casino in July 2025, in the same round as the National Casino action. Bizzo had already been the subject of a 2022 formal warning to TechSolutions (CY) Group Limited and TechSolutions Group N.V. — same brand, two operators, three years. The service is illegal for any Australian resident to access.
Ignition Casino
The ACMA issued a formal warning to Bamboo Media over Ignition Casino in July 2025. Ignition sits in a different operator group from the Dama N.V. and Consolutetish clusters, and the warning is its first appearance in the ACMA’s published register. Australian law prohibits its casino-game offerings.
Instant Casino
The ACMA issued a formal warning to EOD Code SRL over Instant Casino in February 2025. Instant Casino markets itself heavily on PayID deposits; AP+ warns directly that requests to send PayID payments to an illegal site almost certainly means a scam site. The platform has no legal status here.
Jackbit
The ACMA issued a formal warning to Ryker B.V. over Jackbit and CasinOK in April 2026. The warning names two brands under the same operator on the same date — Jackbit and CasinOK marketed as a pair. This remains a prohibited service.
Casino Intense
The ACMA issued a formal warning to Sterplay Holding Ltd over Casino Intense in April 2025. Casino Intense has appeared in AUSTRAC, ITNews and NAB industry coverage as well as in the ACMA’s own register. Online casino games cannot be licensed in Australia, whatever licence the site displays.
Sky Crown
The ACMA issued a formal warning to Hollycorn N.V. over its Sky Crown and Blue Leo casino services. The warning predates the 2025 cluster, but it names the same operator for the same breach — providing prohibited interactive gambling services to Australians. Online casino games cannot be licensed in Australia, whatever licence the site displays.
What the eleven have in common
Every one of these operators has been the subject of an ACMA formal warning under the IGA. Every one offers, or has offered, online casino games and online pokies to customers in Australia. None holds an Australian licence for casino games, because none can. Several share operator parents across two or three brands; the warning is published per brand, but the underlying corporate group is often the same entity the ACMA has warned before. The brand-by-brand list reads like a roll of offshore marketing, and the ACMA’s register reads like the same roll being de-marketed.
Reading the comparison table
| Brand | ACMA action and date | Operator named by the ACMA | PayID support |
|---|---|---|---|
| RocketPlay | Formal warning, March 2026 | Pulsup Ltd | — |
| Level Up Casino | Formal warning, May 2022 | Dama N.V. | Listings only |
| Woo Casino | Formal warning, March 2025 | Dama N.V. | — |
| Spirit Casino | Formal warning, May 2025 | Dama N.V. | — |
| National Casino | Formal warning, July 2025 | Consolutetish S.R.L. | Listings only |
| Bizzo Casino | Formal warning, July 2025; earlier 2022 | Consolutetish S.R.L. | — |
| Ignition Casino | Formal warning, July 2025 | Bamboo Media | — |
| Instant Casino | Formal warning, February 2025 | EOD Code SRL | Listings only |
| Jackbit | Formal warning, April 2026 | Ryker B.V. | — |
| Casino Intense | Formal warning, April 2025 | Sterplay Holding Ltd | Listings only |
| Sky Crown | Formal warning, September 2022 | Hollycorn N.V. | — |
The columns carry what research can back: a date, an operator name, and a marker for whether the brand’s PayID deposit rail is documented by Australian-facing listings rather than by the brand itself. A dash in the PayID column means the brand does not have a verifiable Australian-facing PayID listing in the sources consulted, not that PayID cannot work on the brand’s cashier — the absence is a gap in the public record, not an endorsement. Several of the brands appear across multiple ACMA warnings, and several sit under the same operator group as a brand further up or further down the list; the table flattens that into one row per brand, and the prose above carries the wider picture.
What it costs the country — and what it can cost the player
H2 Gambling Capital’s 2025 report estimates that Australians lose about A$3.9 billion a year to illegal gambling sites, and that the share of gambling going through legal channels fell from 74% in 2021 to 64%. The 3.9 billion is the gross loss Australian households are paying to offshore operators that the ACMA cannot reach directly. The 74% to 64% drift is the legal share shrinking as the illegal share grows — the same customers, the same bank accounts, redirected through PayID and crypto and e-wallets to brands on the ACMA’s block list. The legal wagering market has not shrunk at the same rate; the illegal market has expanded into the gap.
The individual cost is harder to source and harder to generalise. There is no published per-player loss figure for offshore pokies in Australia, because the operators themselves do not report. What the ACMA, AP+ and the banks together make clear is the shape of the risk:
- A blocked site can hold a balance. A blocking request from the ACMA is delivered to ISPs; the offshore site is not notified, and the customer’s account on the site can still be open with money in it. Withdrawals from blocked sites to Australian bank accounts have been reported across multiple brands.
- There is no Australian complaints body. An offshore licence binds the foreign regulator, not the Australian customer. The Australian Financial Complaints Authority does not cover offshore gambling. The customer has, in practical terms, no recourse.
- AP+ considers the request itself a scam signal. Requests to send PayID payments to an illegal site almost certainly means a scam site, in AP+’s own words. The bank’s deposit rail does not protect the customer from this.
The “instant deposit” line on a new PayID pokies site is, mechanically, just NPP speed at the bank. The cost is the A$3.9 billion a year, the blocked balance, the absence of a complaints body, and the ACMA warning already on the file.
What an Australian player actually controls
The legal position puts the entire burden on the player, because the operator side is offshore and outside the IGA’s reach. That is not a reason to despair; it is a reason to know what tools exist.
BetStop and the licensed-wagering register
BetStop — the National Self-Exclusion Register — has been live since August 2023. It binds Australian-licensed online and phone wagering services, which means licensed bookmakers on racing and sport, lotteries and keno. It does not bind offshore pokies sites, because offshore pokies sites are not connected to it. A self-excluded Australian can still open an account on an offshore PayID pokies site, deposit through PayID, and play — BetStop’s protection runs through the licensed side of the market only. For an Australian who wants to exclude themselves from wagering entirely, BetStop covers most of what they would want to exclude themselves from. For an Australian who wants to be excluded from pokies specifically, the offshore gap means BetStop does not finish the job.
The banks’ own gambling blocks
Westpac’s gambling block refuses authorisation of transactions registered under the merchant category code ‘Betting/Casino Gambling’ on eligible personal credit and debit cards. ANZ’s gambling block, activated inside the ANZ app, blocks gambling transactions on eligible cards and on digital wallets such as Apple Pay on the same card. Once ANZ’s block is on, removing it requires a forty-eight-hour waiting period. The banks warn that the blocks are imperfect: not every gambling transaction carries the merchant category code that triggers the block, and some non-gambling transactions may be blocked in error. What the blocks do reliably is close off the card rail at the bank level. What they do not do is change the legality of the offshore site, and they do not cover transfers through PayID that originate from a non-blocked account or a non-blocked institution.
Support lines that are actually Australian
The National Gambling Helpline is 1800 858 858 — free, twenty-four hours a day, with web chat at Gambling Help Online. The helpline is funded for Australian residents, by Australian state and territory governments, and is not connected to any offshore operator. It is the single line that will not try to sell anything, will not ask for a deposit, and will not route the caller back into a casino. The minimum age for any Australian wagering service, licensed or otherwise, is eighteen.
Tax position for the recreational player
Gambling winnings of a recreational player are not assessable income under section 6-5 of the Income Tax Assessment Act 1997, and losses are not deductible — unless the person carries on a business of gambling, which is a different question entirely. The position is the same whether the win came from a licensed bookmaker or from an offshore PayID pokies site. The Australian Taxation Office treats the recreational case as not taxable; the Australian Taxation Office does not, on that basis, license or legitimise the offshore site.
The 2026 reform — law with a start date, not yet in force
The Interactive Gambling Amendment (Gambling Reform) Bill 2026 passed Parliament on 19 August 2026. Its advertising and inducement measures commence on 1 January 2027. This is a law with a start date: passed, but not yet in force on a page written in 2026. The new measures are aimed at licensed wagering operators’ advertising and at inducements to use prohibited services. They do not, on the text as published, change the underlying prohibition on providing online casino games to Australians, which is the IGA’s existing offence and the basis on which the ACMA’s eleven formal warnings already rest. The reform changes what licensed operators can advertise; it does not legalise offshore pokies, and it does not extend BetStop or any Australian consumer protection to offshore sites. A reader comparing new pokies sites in 2026 is still reading the IGA as it stood before the reform, plus the ACMA warnings that have piled up under it.
What the speed is actually worth
The Osko transfer through PayID arrives in under a minute, twenty-four hours a day, weekends included. That is the headline number every new PayID pokies site borrows. The same speed, in the same banking app, applies to a transfer to a plumber, a transfer to a friend splitting a bill, and a transfer to an ACMA-warned offshore casino. The speed is the NPP’s, not the casino’s. The bank will not distinguish between the three on the way in. The ACMA, the bank, and AP+ all distinguish between them on the way out: a blocked casino is still blocked, a gambling-blocked card still refuses the authorisation, and a PayID transfer to a “scambling” site still carries the scam warning AP+ has published.
A new pokies site that takes PayID is using a deposit rail every Australian already trusts to send money to family. The trust does not transfer. The ACMA’s eleven formal warnings, the 1,751 blocked sites since November 2019, the A$3.9 billion a year in losses to illegal sites, and the licensed-channel share dropping from 74% to 64% are the actual record. The speed is real, and so is everything else.
Frequently asked questions
What is PayID, and why do new pokies sites keep advertising it as a deposit method?
PayID is an easy-to-remember alias for an Australian bank account — a mobile number, email address, ABN or Organisation Identifier — built into the online banking of more than 100 Australian financial institutions. New pokies sites advertise it because the deposit goes through the customer’s own banking app and clears in under a minute through Osko. The speed is the New Payments Platform’s, not the casino’s. AP+ warns that transferring funds to a PayID on an illegal gambling site almost certainly indicates a scam, and online casino games cannot be licensed in Australia regardless.
Does using PayID make a new offshore pokies site any safer or more legitimate for an Australian player?
No. PayID is a payments rail operated by Australian Payments Plus, not a consumer-protection regime. The IGA makes it an offence to provide online casino games to a person in Australia, and the ACMA has issued formal warnings over the eleven brands listed on this page alone. PayID cannot change the licence the offshore site does not hold, and a PayID transfer does not give an Australian player any recourse through the Australian Financial Complaints Authority if a withdrawal is refused.
How quickly does an Osko transfer through PayID actually settle compared with a card deposit?
An Osko transfer through PayID arrives in under a minute, twenty-four hours a day including weekends. A card deposit at an offshore casino is, on the same banking app, subject to the bank’s own authorisation step and the merchant category code rules; ANZ and Westpac both block gambling transactions at the card level on eligible cards, and ANZ extends its block to digital wallets such as Apple Pay on the same card. The PayID route is faster in the clean case, but the card route is the one the bank is most likely to block.
Why would a brand-new pokies site suddenly add PayID support?
Because PayID gives the site a deposit rail that does not require a card network, does not require a crypto wallet, and clears through the customer’s own banking app in under a minute. For an offshore operator marketing to Australians, that combination looks like trust borrowed from the bank. The ACMA has warned eleven brands operating in this market for offering prohibited services to Australians, and PayID support does not change the legal status of the offer.
Is it legal for an Australian to send money via PayID to an offshore pokies operator?
The Interactive Gambling Act 2001 targets the provider, not the individual player; an Australian who sends money to an offshore pokies site is not personally prosecuted under the IGA. The provider is the offending party. That does not make the transfer safe: an offshore site gives no Australian consumer protection, no complaints body and no recourse if a withdrawal is refused, and the ACMA can ask ISPs to block the site with the customer’s balance still on it.